by paulina@baraibar.com.mx | Jun 25, 2026 | Administrative Law
The 2026 Federal Law on Administrative Litigation (LFPCA) reform, which came into effect on June 10, 2026, represents one of the most significant changes to federal administrative litigation since the consolidation of the Online Justice System. Published in the Official Gazette of the Federation on June 9, 2026, this reform profoundly alters how companies and individuals must defend their rights before the Federal Court of Administrative Justice (TFJA). Therefore, if your company has ongoing tax, customs, or administrative litigation—or anticipates it in the near future—this analysis is essential to avoid being at a procedural disadvantage.
LFPCA Reform 2026, why does it mark a before and after?
The Federal Law of Administrative Litigation Procedure (LFPCA) regulates the legal process through which individuals and companies challenge resolutions issued by federal authorities, primarily the Tax Administration Service (SAT), the Ministry of Finance and Public Credit (SHCP), the Mexican Social Security Institute (IMSS), and various regulatory agencies. However, prior to this reform, the legal framework lacked mandatory deadlines for the Tribunal's actions, leading to procedural uncertainty and unpredictable resolution times.
The 2026 LFPCA reform substantially changes this paradigm. First, it imposes specific deadlines for the TFJA to carry out actions that previously lacked a legal timeframe. Furthermore, it deepens the digitization of the procedure and expands the summary procedure. However, and this is crucial, it also redistributes procedural burdens to the detriment of the individual: it reduces the value of annulments due to procedural defects and grants the authority broader discretion to reinstate annulled acts.
Consequently, the reform is not neutral. It requires litigants to rethink their strategy from the initial pleading stage, strengthen their substantive arguments, and more rigorously monitor the electronic case file and notifications via the Jurisdictional Bulletin.
| ⚖️ Do you have questions about this reform? The lawyers at Baráibar & Asociados in Mexico City can guide you. Schedule your consultation today. |
New mandatory deadlines: the LFPCA reform 2026 sets time limits for the TFJA
One of the most visible changes in the 2026 LFPCA reform is the incorporation of express deadlines for actions that previously lacked a legal time limit. Similarly, limits are established for procedural acts by the parties. Among the most relevant are the following:
The Federal Court of Administrative Justice (TFJA) will have five business days to rule on any motion unless the law establishes a different deadline. This same timeframe also applies to admitting or dismissing claims, amendments, responses, and appearances, once the corresponding preliminary requirements have been met. The final judgment in summary proceedings must be issued within a maximum of six months from the date the claim is admitted, subject to suspensions resulting from incidental proceedings or appeals.
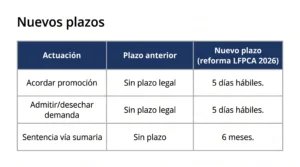
Comparison of procedural deadlines
However, it is important to emphasize that failure to meet these deadlines does not, in itself, result in a deemed resolution or the automatic loss of jurisdiction of the court. Its practical effectiveness will depend on the oversight and enforcement mechanisms provided for in the Law. Therefore, having specialized legal counsel is essential to take advantage of these deadlines as a defense tool.
Digitization of the trial: hybrid file and electronic notifications
The 2026 LFPCA reform takes a further step in the digitization of administrative litigation. Although individuals retain the right to choose between traditional and online proceedings, the reform allows the defendant authority and third parties to appear and submit arguments electronically, even within a case being processed through traditional means. In such cases, the TFJA (Federal Court of Administrative Justice) must print and certify the electronic filings and documents for inclusion in the physical case file.
However, the most critical change for businesses is the modification to the notification system via the Jurisdictional Bulletin. Once the new Article 65 is in effect, the notification will take effect on the second business day following publication, instead of the third business day previously stipulated. This reduces the litigant's time to react. Therefore, maintaining daily and independent monitoring of the Bulletin—without relying exclusively on email notifications—becomes an urgent and practical necessity.
Likewise, when submitting digitized documents, the applicant must declare, under oath, whether they are originals, certified copies, or simple copies. Failure to do so will create a presumption, to the detriment of the offeror, that the document is a simple copy.
Expansion of the summary procedure: benefit or strategic trap?
The 2026 LFPCA reform expands the scope of summary proceedings by increasing the threshold amount from fifteen to thirty times the Unit of Measurement and Update (UMA) per year. It also expressly incorporates resolutions issued by tax authorities in response to refund requests for overpayments or payments made in error. In principle, this may reduce the time required for disputes involving small and medium amounts.
However, the summary procedure also reduces the time available to obtain documents, prepare expert opinions, or gather technical information during the proceedings. Therefore, if your case falls under this procedure, the lawsuit must be filed with a practically complete theory of the case and evidentiary record from the outset. Similarly, the grounds for appeal must be solid and focused on the merits, because the time to develop them after filing the lawsuit will be minimal.
| 📋 Don't face this process alone. At Baráibar & Asociados, we have specialists in Administrative and Tax Law ready to defend your interests in Mexico City. |
Changes in the suspension of the contested act: less burden, more risks
The reform eliminates the requirement to prove that the execution of the challenged act could cause irreparable harm or damage. This ostensibly facilitates access to provisional relief. Therefore, obtaining a stay of the act should, in theory, be simpler for the individual.
However, the reform introduces two new scenarios in which a suspension will be considered to affect the public interest or violate public order: when it allows the continuation of activities requiring federal permits, authorizations, or concessions without them; or when it allows the commission or continuation of conduct that constitutes an infraction or crime. For companies in regulated sectors—energy, telecommunications, finance, and customs—these categories represent a real risk. In these cases, the suspension request must precisely define its effects and demonstrate that the measure only preserves the subject matter of the lawsuit.
Formal nullities and replacement of acts: strategic impact for companies
One of the most strategically impactful changes of the 2026 LFPCA reform concerns the reinstatement of actions annulled due to procedural or formal defects. The tax authority will have four months to reinstate the procedure and issue a new resolution—or one month in summary proceedings—even if, in tax matters, the time limits established in Articles 46-A, 50, or 67 of the Federal Tax Code have expired.
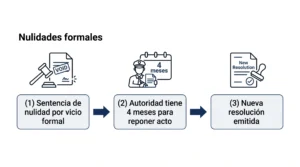
When there is nullity due to formal defects, the authority can replace the act within 4 months.
This amendment reduces the possibility that a formal annulment could, simply through the passage of time, become a definitively favorable ruling for the individual. Therefore, defense strategies based solely on procedural or formal defects lose some of their effectiveness. Instead, it will be necessary to strengthen substantive appeals and expressly request an analysis of the substantive arguments. It is worth noting that, as a counterbalance, the reform does strengthen the mechanisms for enforcing judgments: it shortens deadlines and allows for fines of 300 to 1,000 times the UMA (Unit of Measurement and Update) against authorities who unjustifiably fail to comply.
Expanded tax review: the 2026 LFPCA reform and ANAM on the scene
The 2026 LFPCA reform also modifies the tax review process. The general threshold for the amount in controversy is set at 27,000 times the Unit of Measurement and Update (UMA) in effect at the time of the resolution or judgment. Furthermore, certain resolutions issued at the complaint stage are included, and the National Customs Agency of Mexico (ANAM) and its administrative units are expressly recognized as authorities authorized to file appeals in matters within their jurisdiction.
In practice, this means that a favorable ruling based solely on procedural violations may cease to be final in high-value disputes. Likewise, in the customs arena, the express incorporation of the ANAM reinforces the need to build a technically sound case file from the outset in matters of tariff classification, customs valuation, origin of goods, and non-tariff regulations. However, the reform also opens the door to greater procedural certainty in lower-value cases where tax review is no longer applicable.
| ⚖️ Protect your company's rights with expert legal advice from Baráibar & Asociados. Contact us today. |
Conclusion: the 2026 LFPCA reform requires a more strategic defense from the outset
The 2026 LFPCA reform is not a minor technical update. It is a turning point that requires a rethinking of litigation strategy in administrative courts. Therefore, companies with current or future litigation before the TFJA must take immediate action: classify their cases according to the rules of deferred effect, strengthen their monitoring of the Jurisdictional Bulletin, prepare advance evidentiary files, and review the strength of their substantive arguments.
At Baráibar & Asociados, our specialists in Administrative and Tax Law in Mexico City are ready to guide you through this transition. Schedule a consultation and protect your company's interests under the new procedural framework.
Frequently Asked Questions about the LFPCA 2026 Reform
1. When did the LFPCA 2026 reform come into effect?
The 2026 Federal Law on Administrative Procedure (LFPCA) reform entered into force on June 10, 2026, one day after its publication in the Official Gazette of the Federation (DOF), with the exception of certain provisions with deferred implementation (Article 6 Bis in February 2027 and hybrid procedures in December 2026). Legal basis: Transitory Article One of the Decree published on June 9, 2026.
2. What is the deadline for the TFJA to agree to a promotion under the LFPCA 2026 reform?
The Federal Court of Administrative Justice (TFJA) has five business days to rule on any motion unless otherwise specified by law. This same timeframe applies to admitting or dismissing claims and responses. However, failure to meet this deadline does not, in itself, result in a deemed decision or loss of jurisdiction. Basis: new Article 6 Bis of the Federal Law of Administrative Procedure (LFPCA).
3. Does the burden of proof change in order to obtain the suspension of the challenged act?
Yes. The 2026 LFPCA reform eliminates the requirement to prove irreparable damages. However, it introduces two new grounds for harm to the public interest: activities that require authorization but lack it, and conduct that constitutes an infraction or crime. Companies in regulated sectors should carefully evaluate their case before requesting a suspension. Basis: reforms to Articles 24 and 28 of the LFPCA.
4. What if the authority annuls my act due to a procedural defect under the new law?
The authority will have four months (one of which will be a summary proceeding) to reinstate the procedure and issue a new ruling, even if the time limits established in Article 46-A or 67 of the Federal Tax Code have expired. This reduces the strategic advantage of formal annulments and reinforces the importance of also challenging the merits of the case. Legal basis: new Article 52, last paragraph, Federal Law of Administrative Procedure.
5. What is the hybrid file in the LFPCA 2026 reform?
This is the system that allows the defendant authority and third parties to submit electronic documents within a trial conducted through traditional means. The Federal Court of Administrative Justice (TFJA) must print and certify the electronic documents for inclusion in the physical case file. This provision will enter into force on December 6, 2026. Legal basis: Article 19, second paragraph as amended, and Transitory Article Five of the Federal Law of Administrative Procedure (LFPCA).
6. Can ANAM initiate the tax review process?
Yes. The 2026 LFPCA reform expressly recognizes the National Customs Agency of Mexico and its administrative units as authorities authorized to file tax review appeals in matters within their jurisdiction, provided that the threshold of 27,000 times the UMA (Unit of Measurement and Update) is met. Legal basis: Article 63, amended sections, LFPCA.
Legal references:
🔗 DOF — Decreto que reforma la LFPCA, 9 de junio de 2026
🔗 Tribunal Federal de Justicia Administrativa — TFJA
🔗 Strategic Guide — Reform to the Amparo Law 2025 for companies
🔗 Statute of limitations for civil liability for created risk: 10 years
This article is for informational purposes only and does not constitute formal legal advice or establish an attorney-client relationship.
by paulina@baraibar.com.mx | Jun 8, 2026 | Constitutional Law
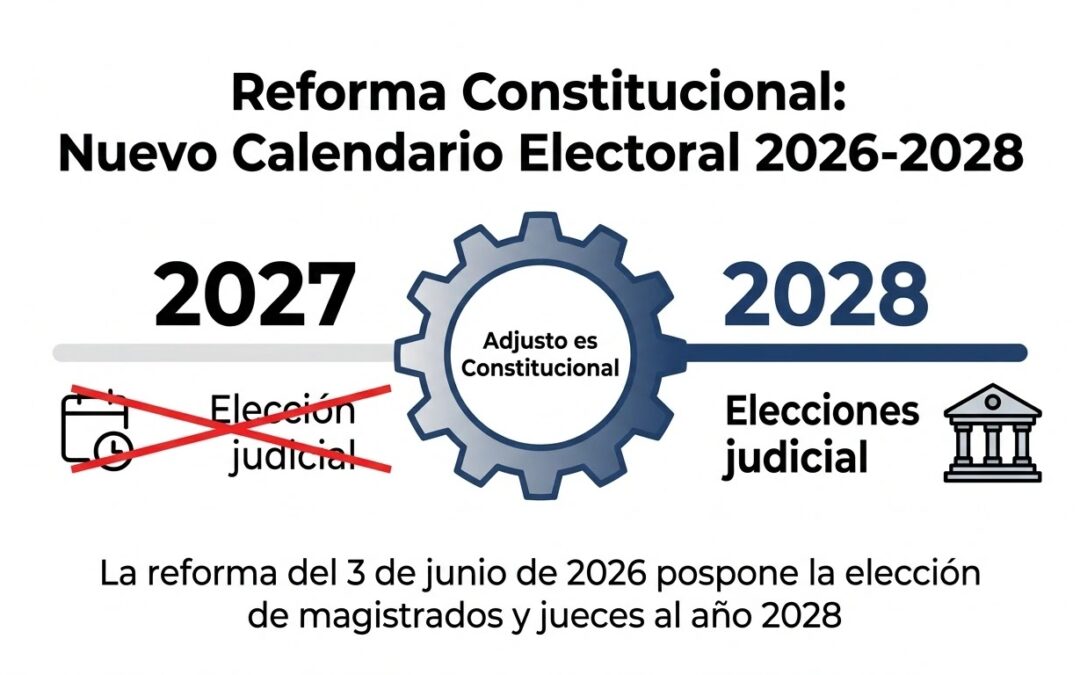
El 3 de Junio de 2026, entró en vigor La reforma constitucional que entró en vigor ayer, 3 de junio de 2026, redefine el calendario electoral y fortalece la integridad de los procesos democráticos en México. Publicada en el Diario Oficial de la Federación el 2 de junio de 2026, esta reforma constitucional junio 2026 contiene tres cambios fundamentales que afectan directamente la certeza jurídica de empresas, ciudadanos y autoridades en todo el país.
What is the Constitutional Reform of June 3, 2026?
The constitutional reform of June 2026 modifies the electoral deadlines and grounds through three separate decrees published in the evening edition of the Official Gazette of the Federation (DOF). However, the most significant change is the postponement of the judicial elections from 2027 to 2028. Therefore, the Federal Judiciary will not elect magistrates and judges in 2027, as initially planned.
Entre los cambios aprobados, destaca la incorporación de la intervención o injerencia extranjera como nueva causal de nulidad electoral, una figura que requerirá de prueba clara y contundente para sostenerse. De igual forma, la reforma a la Ley General de Instituciones y Procedimientos Electorales contempla la creación de una comisión verificadora de la probidad de los candidatos.
First Change: Postponement of the Judicial Election to 2028
Originally, the 2024 judicial reform stipulated that the election of magistrates and judges would take place in June 2027. However, this constitutional reform of June 2026 postpones that process to 2028. The reason: it allows for the consolidation of institutional changes and generates greater certainty in the federal justice system.
Este aplazamiento tiene implicaciones críticas para empresas litigantes. En consecuencia, los criterios actuales de los jueces federales se mantienen vigentes durante 18 meses adicionales. En consecuencia, los criterios actuales de los jueces federales se mantienen vigentes durante 18 meses adicionales. Asimismo, los abogados deben actualizar sus estrategias litigiosas considerando que no habrá renovación de la judicatura en 2027.
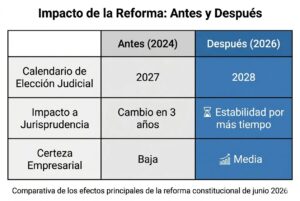
Comparison of the main effects of the constitutional reform of June 2026
Second Change: New Ground for Electoral Nullity — Foreign Intervention
Furthermore, the constitutional reform incorporates proven foreign intervention or interference in the electoral process as grounds for electoral annulment. This new provision responds to international concerns regarding the integrity of the vote. It is important to note that the National Electoral Institute (INE) must prove the causal link between the interference and the electoral outcome.
Las implicaciones para empresas transnacionales son claras: están prohibidas de participar en financiamientos electorales, aun indirectamente. Un caso claro ocurre cuando las aportaciones a organizaciones terminan financiando campañas, lo cual puede constituir injerencia extranjera. En consecuencia, el cumplimiento normativo electoral es más exigente que antes.
⚖️ Do you have questions about this topic? The lawyers at Baráibar & Asociados in Mexico City can guide you. Schedule your consultation today.
Third Change: Candidate Integrity Verification Commission
Con la llegada de un órgano especializado en vigilar la probidad de los candidatos, las investigaciones sobre los aspirantes se centrarán únicamente en sus registros fiscales, penales y administrativos. No obstante, al tener competencias limitadas, la potestad definitiva para invalidar una postulación se mantendrá bajo la jurisdicción del INE.
Cuando hay socios o accionistas que aspiran a cargos públicos el impacto para empresas es significativos. En primer lugar, sus antecedentes serán escrutados públicamente. Además, cualquier incumplimiento fiscal o administrativo puede impactar sus capacidades políticas.
Evaluation of the Current Legal Context
The Mexican Bar Association (BMA) issued a critical statement on June 2, warning that these reforms do not correct the structural problems stemming from the 2024 judicial reform. In fact, postponing the judicial election generates additional economic uncertainty.
Dentro del sector empresarial se tiene la inquietud se ha hecho evidente ante la continuidad de juzgadores con posturas consideradas de alto riesgo. A esto se suma el impacto del nuevo requisito de probidad electoral sobre los candidatos del ámbito corporativo, una medida que limita la pluralidad de perfiles en las boletas electorales.
However, experts consulted point out that the postponement to 2028 allows the new institutions created by the 2024 reform to consolidate. Therefore, the measure is pragmatic, albeit temporary.
📋 Don't face this process alone. At Baráibar & Asociados, we have specialists in Constitutional Law ready to defend your interests in Mexico City.
Immediate Obligations for Businesses and Citizens
In addition to complying with the new electoral regulations, companies must audit their relationships with candidates and political parties. It is important to note that any contribution, even indirect, can be classified as foreign interference if it involves foreign entities.
Los ciudadanos deben entender que el nuevo estándar de probidad electoral es más riguroso. No obstante, las garantías del debido proceso se mantienen; de igual manera, las decisiones de la comisión verificadora pueden impugnarse ante los órganos electorales correspondientes.
In conclusion, the constitutional reform of June 2026 is not a radical change, but it does represent significant adjustments. Therefore, expert advice is more valuable than ever to navigate this new legal landscape.
Regulatory Sources and Legal Reference
🔗 EXTERNAL LINK: Official Gazette of the Federation – Amendments of June 2, 2026 → https://dof.gob.mx
🔗 EXTERNAL LINK: Suprema Corte de Justicia de la Nación – Información sobre Reforma Judicial → https://www.scjn.gob.mx
🔗 EXTERNAL LINK: Barra Mexicana Colegio de Abogados – Comunicado de Posición → https://www.bma.org.mx
Frequently Asked Questions (FAQs)
- Does the constitutional reform of June 2026 affect active litigation processes?
No, no afecta procedimientos vigentes, solo modifica el calendario electoral. Sin embargo, el aplazamiento de la elección judicial mantiene los criterios interpretativos actuales por más tiempo. Por ello, la jurisprudencia existente sigue siendo vinculante hasta 2028. Los litigios en curso se resuelven conforme a las normas aplicables al momento de promover la acción.
- What are the penalties for proven foreign election interference?
Aunque el texto de la reforma no especifica un catálogo de sanciones, estas se remitirán directamente a lo establecido en el Código Penal Electoral. Asimismo, se contempla la posibilidad de declarar la nulidad de los comicios donde se determine injerencia, con la condición de que la prueba sea inequívoca y se acredite ante el INE.
- What does ‘probity’ mean in the context of the verification commission?
Probity means moral integrity and rectitude in the exercise of public functions. The commission verifies criminal, administrative, and tax records. It also investigates declared conflicts of interest. However, the standards of ‘probity’ vary according to the electoral body's interpretation.
- Can the decisions of the probity verification commission be challenged?
Yes. Candidates may file administrative appeals and electoral litigation. However, the procedure must be completed before the candidate registration period closes. Likewise, the burden of proof rests with the party challenging the commission's decision.
- Are the eligibility requirements for candidates changing?
Not in a formal sense. The age, nationality, and residency requirements remain the same. However, the new integrity filter adds a de facto requirement: no serious criminal, administrative, or tax record. Therefore, access to candidacies becomes more selective.
- Until when will the postponement of the judicial election to 2028 be valid?
The postponement is enshrined in the reform and can only be modified through a new constitutional amendment. Similarly, it would require approval in both houses of Congress and 50% of state legislatures. Therefore, it is virtually irreversible within the current presidential term.
Protect your rights with expert legal advice from Baráibar & Asociados. Contact us in Mexico City for a tailored constitutional strategy.
Disclaimer
This article is for informational purposes only and does not constitute formal legal advice or establish an attorney-client relationship. Legislative changes can be interpreted in multiple ways depending on specific contexts. Always consult with a qualified attorney before making decisions based on these regulations.
by paulina@baraibar.com.mx | Jun 3, 2026 | Constitutional Law, Corporate Law
Baráibar & Asociados | Análisis Jurídico Estratégico
The reform to the Amparo Law 2025The ruling, published on October 16 in the Official Gazette of the Federation, reshaped the constitutional framework in Mexico. Every company with operations in Mexico City needs to understand the true scope of these changes before its next conflict with a tax or administrative authority.
This isn't about technical adjustments. It's about a structural shift in the amparo proceedings: tax matters, suspensions of the challenged action, judicial digitization, and retroactive application. Companies that don't update their legal strategy will be exposed to risks that, six months ago, were easily defensible.
At Baráibar & Asociados, we analyzed the decree and its operational impact on businesses, real estate companies, and corporations in Mexico City. This guide explains the critical points, hidden risks, and strategic decisions your company should make this quarter.
What changed with the 2025 reform to the Amparo Law? This guide explains the critical points, hidden risks, and strategic decisions your company should make this quarter.
What changed with the 2025 reform to the Amparo Law? This guide explains the critical points, hidden risks, and strategic decisions your company should make this quarter.
The reform is based on four pillars: digitization of the Services Portal of the Federal Judiciary, restriction of amparo in tax matters, modification of the rules of suspension of the challenged act and a retroactive transitional provision that most constitutional experts consider openly unconstitutional.
Each of these measures has direct consequences for businesses in Mexico City. Digitalization requires businesses to have legal representation registered on the electronic portal. Tax restrictions close doors that for decades protected taxpayers from enforceable tax assessments. The new suspension rules expand exemptions for public entities. The retroactive transitional provision also opens a window for constitutional litigation that only specialized law firms are prepared to navigate.
Mandatory judicial digitization: the new Services Portal of the Federal Judiciary
The reform prioritizes electronic filing as the primary means for amparo proceedings. Responsible authorities, third parties, and petitioners must operate through the Online Services Portal of the Federal Judiciary. Physical filing of documents is no longer the rule but becomes an exception reserved for very specific cases.
Therefore, electronic notifications acquire full procedural validity, and deadlines begin to run from the date of the consultation or the legal presumption of consultation. Furthermore, the responsible authorities must digitize actions, administrative files, and records that were previously presented on paper, which accelerates the process but also makes it less forgivable for oversights.
Consequently, a modern firm needs a law firm with valid e-signature certificates, internal infrastructure for receiving electronic notifications, and a clear protocol for digital case tracking. A 48-hour delay in checking the portal can result in preclusions, fines, or the loss of proceedings. Firms still operating with traditional practices face an operational risk even greater than the underlying risk of the case itself.
⚖️ Do you have questions about how the reform to the Amparo Law affects you?
The lawyers at Baráibar & Asociados in Mexico City can guide you.
Schedule your appointment today.
Restrictions on tax protection: the shield was reduced
The most significant change for businesses is the restriction on legal protection against final tax assessments. Previously, a company could challenge the merits of an assessment even after it became final, alleging substantive violations during its enforcement. Historically, this loophole saved companies with millions of dollars in debt stemming from poorly substantiated tax audits by the Mexican Tax Administration Service (SAT).
Today, the amparo proceeding is only admissible against acts of execution or collection, up to the publication of the auction notice, and only for violations that occurred within the administrative execution procedure. The scope is limited to procedural errors in the collection process, not to the original debt. The merits of the case are no longer addressed in this final stage.
Consequently, the traditional strategy of appealing at the end of the process has been ruled out. If the company did not properly defend itself from the initial assessment of the credit—or from the appeal for reconsideration, or from the administrative litigation—its subsequent recourse is limited to procedural flaws that are almost always minor and rarely decisive.
What it was like before the reform
Before October 17, 2025, taxpayers could challenge a final tax assessment through indirect amparo proceedings when they detected constitutional violations that had not been previously identified. This amparo was, in practice, a second chance for companies with multimillion-dollar assessments or with rulings that could be challenged due to supervening unconstitutionality. The Supreme Court of Justice of the Nation (SCJN) had established consistent criteria that kept this avenue of effective constitutional protection open.
What has changed and when is legal protection now available?
However, the reform limits this second opportunity. The injunction is only applicable against the enforcement proceedings, not against the underlying debt. Furthermore, it must be filed before the publication of the auction notice, not afterward. In conclusion, companies with debts under review must act now, before their cases reach a final stage and they lose effective constitutional protection.
Suspension of the contested action: new rules affecting companies
The suspension is the mechanism that prevents an authority from carrying out an action while the injunction is being resolved. Without a suspension, there is no effective injunction. The reform modified two key aspects of this mechanism: the granting of guarantees and exemptions for public entities, two components that underpin any serious business defense strategy.
On the one hand, the criteria for granting injunctions were tightened in fiscal, financial, and administrative matters. The district judge now requires stronger evidence of a prima facie case, irreparable harm, and public interest. On the other hand, public entities, decentralized agencies, and state-owned enterprises obtained exemptions that allow them to suspend challenged actions without providing financial security.
In practice, this combination creates an uncomfortable procedural asymmetry: the private sector must prove more to obtain a suspension, while the public sector accesses suspensions with fewer requirements. Companies litigating against authorities or state-owned enterprises face a more challenging playing field than just two years ago.
Guarantees, exceptions, and margins of defense
Therefore, companies need to provide robust evidence for each of the requirements for a stay of proceedings: prima facie case, irreparable harm, and the absence of prejudice to public order or the public interest. A poorly substantiated petition can deny the stay and expose the company to seizures, closures, or the freezing of bank accounts. Consequently, the technical expertise of the law firm matters more than ever, and the difference between amateur and premium litigation lies in the guarantees effectively provided.
Retroactivity: the transitional provision that generated constitutional alarm
The most controversial aspect of the reform is a last-minute transitional provision that allows the changes to be applied to trials initiated before the reform takes effect. The Mexican Constitution expressly prohibits the retroactive application of laws to the detriment of any person in Article 14. Few rules in our national legal system are as clear and as long-standing.
Therefore, this transitional provision is, in the opinion of most constitutional experts, blatantly unconstitutional. Companies with pending injunctions now face the possibility that their procedural rules may change mid-trial. This undermines the legal certainty that underpins any serious business defense strategy and discourages investment.
However, the unconstitutionality of the transitional provision paradoxically opens a strategic avenue: directly challenging its retroactive application through a new injunction. This litigation could establish legal precedent and protect all companies in similar situations. Furthermore, top law firms are building precedents in various circuits to challenge this transitional provision. The first rulings, expected in the second half of 2026, will set the standard for the entire Mexican business sector.
📋 Don't face this process alone.
At Baráibar & Asociados we have specialists in Amparo and Constitutional Litigation ready to defend your interests in Mexico City.
Impact on corporate defense strategy: from litigation to lobbying
The reform has brought about a paradigm shift in corporate defense. Companies that historically relied on injunctions as a bulwark are now exploring other avenues. Institutional lobbying, administrative mediation, international arbitration, and negotiation with authorities have become essential components of modern legal strategy.
However, this does not mean that constitutional litigation is dead. It means that it can no longer be improvised. Every action must be planned from the outset, starting with prevention and the first act of authority, not at the end of the process. Legal planning replaces legal reaction, and boards of directors must update their risk matrices.
Strategic litigation still viable
The amparo proceeding remains the most powerful tool in Mexican law. However, it demands impeccable preparation, robust documentary evidence, and a legal team with proven constitutional experience. Companies that continue to treat amparo as a last resort will lose out; those that integrate it into their corporate governance and compliance matrix will gain decisive advantages in their defense.
Arbitration and mediation as alternatives
On the other hand, international arbitration and administrative mediation allow for the resolution of disputes outside the judicial system. These avenues are gaining ground in the corporate, energy, real estate, and technology sectors. Furthermore, they offer predictability, confidentiality, and speed that Mexican courts do not guarantee, especially in a judicial environment undergoing significant restructuring.
What should businesses in Mexico City do? Preventive checklist
In the face of a regulatory change of this magnitude, prevention far outweighs reaction. Companies in Mexico City must immediately review their contracts, their tax exposure, and their map of active litigation. Furthermore, they should update their defense strategy with their primary law firm and inform their board of directors of the new situation.
- Audit all tax credits under review or to be determined before they reach a final stage.
- Review the arbitration and jurisdiction clauses of current contracts with suppliers, partners, and authorities.
- Strengthen the internal compliance area and the protocols for immediate response to acts of authority.
- Request the firm to conduct a specific analysis of how the retroactive transitional provision affects any ongoing injunctions.
- Update the board of directors' legal risk map with a focus on tax and administrative matters.
Finally, it is advisable to establish a direct line of communication with a law firm specializing in constitutional protection and litigation. In this new environment, speed of response is as important as the technical quality of the document.
🛡️ Anticipate the risks of the new Amparo Law.
Baráibar & Asociados offers preventative analysis and specialized defense for companies that cannot afford to improvise.
Conclusion: a new stage for the defense of the Mexican Constitution
The 2025 reform to the Amparo Law marks the beginning of a new era for Mexican business law. Constitutional protection remains, but it demands sophistication, anticipation, and boutique-level legal support. Amparo is no longer a reactive measure but has become a key element of preventative strategy.
Companies that take action this quarter will be better positioned with the tax authorities, the judiciary, and other administrative bodies. Those that wait will discover that the protection they took for granted has been reduced and that rebuilding it too late costs far more than preventing problems in time.
Frequently asked questions about the 2025 reform to the Amparo Law
When did the 2025 reform to the Amparo Law come into effect?
The reform was published in the Official Gazette of the Federation on October 16, 2025, and entered into force on October 17 of the same year, pursuant to the First Transitory Article of the decree. It applies to all proceedings initiated from that date and, controversially, also to certain pending matters by virtue of a transitional provision.
Does the reform to the Amparo Law apply retroactively to trials in progress?
Yes, according to a transitional provision challenged as unconstitutional under Article 14 of the Constitution, which prohibits retroactive application to the detriment of any person. Companies with existing injunctions can challenge this application through a new constitutional lawsuit, which is generating valuable precedents in specialized courts.
What tax changes did the reform to the Amparo Law bring?
The injunction against final tax assessments is restricted to acts of enforcement or collection, up to the publication of the auction notice, and only for violations of the enforcement procedure, pursuant to Article 107 of the amended Amparo Law. It precludes challenging the substance of the original assessment.
Can my company continue to file for protection against SAT resolutions?
Yes, but the correct procedural moment has passed. It's advisable to file for amparo (constitutional protection) from the moment the debt is determined, the appeal for reconsideration is filed, or the administrative litigation begins, not at the end. After the judgment becomes final, amparo is only available against procedural defects, which significantly reduces the scope for effective defense.
What is the suspension of the challenged act and how does it change with the reform?
It is the precautionary measure that prevents the execution of the act while the amparo (constitutional protection) is being resolved, regulated in Article 128 of the Amparo Law. The reform tightens the requirements for private individuals and expands guarantee exemptions for public entities, creating a procedural asymmetry that requires technically strengthened written submissions from companies.
What alternatives does my company have if the injunction is restricted?
The main options are domestic or international commercial arbitration, administrative mediation, institutional lobbying, and negotiation with authorities. Additionally, a proactive strategy encompassing tax compliance, contracts, and corporate governance reduces the need for litigation. The writ of amparo remains in effect, but as an integrated tool, not as the sole remedy.
Legal references
Amparo Law, Regulating Articles 103 and 107 of the Political Constitution of the United Mexican States (last amendment published in the Official Gazette of the Federation on October 16, 2025). https://www.diputados.gob.mx/LeyesBiblio/ref/lamp.htm
Constitución Política de los Estados Unidos Mexicanos, artículos 14, 103 y 107. Cámara de Diputados del H. Congreso de la Unión. https://www.diputados.gob.mx/LeyesBiblio/
Suprema Corte de Justicia de la Nación. Buscador Jurídico de Tesis y Jurisprudencia. https://bj.scjn.gob.mx/
Diario Oficial de la Federación, edición del 16 de octubre de 2025. https://www.dof.gob.mx/
Disclaimer: This article is for informational purposes only and does not constitute formal legal advice or establish an attorney-client relationship.
👉 Schedule a legal consultation at Baráibar & Asociados.
by paulina@baraibar.com.mx | May 27, 2026 | Uncategorized
The labor certification for agricultural exports It's no longer just an idea: since the May 1, 2026 (Official Gazette, evening edition) the Article 283 Quater to the LFT so that the STPS may issue a certificate of compliance with labor and social security regulations, with operating rules to be issued within 30 days. In parallel, the Ley de Comercio Exterior to incorporate assumptions linked to deforestation/land use change and ecology as a basis for measures in foreign trade. (Cámara de Diputados)
For agricultural exporters and supply chains (agro/forestry), the message is clear: the market and the authorities are aligning towards low tolerance facing risks labor, social security and environmental.
What exactly changed in the Official Gazette of the Federation (DOF) of May 1, 2026? (and… why does it matter?)
The Decree published in the evening edition amends three parts:
- Foreign Trade Law, Article 15, sections IV and VI
- The following is expressly incorporated: prevention of deforestation and unauthorized land use change in forest areas as an assumption for measures.
- The spectrum of “situations not foreseen by NOM” is broadened to include ecologyand it also connects with work and social security. (Cámara de Diputados)
- Federal Labor Law, Article 283 Quater (new)
- “The STPS may issue a certificate of compliance with labor and social security obligations”, in accordance with general provisions issued by competent authorities. (Cámara de Diputados)
- Key transient
- STPS must issue rules/procedures in 30 days counted from the date of entry into force (entry into force was the day after publication). (Cámara de Diputados)
Why it matters: Article 15 LCE is the “legal gateway” to non-tariff regulatory or restrictive measures (permits, certifications, etc.) in export and import. In agricultural exports, this translates into controls of evidence gathering, traceability and auditingIf your operation cannot demonstrate "lawful origin" (environmental) and "compliance" (labor/SS), your risk is no longer theoretical: it is operational (customs, clients, contracts, financing).
New “environmental” grounds in foreign trade: from regulation to customs risk
How does Article 15 of the LCE operate in practice?
The article 15 allows you to establish non-tariff measures on exports in specific cases. With the reform, section IV expressly includes prevent deforestation and unauthorized change of forest land use. (Cámara de Diputados)
This does not automatically create a new “environmental permit” the next day; what it does is legally enable to the authority to design measures in foreign trade (e.g., documentary requirements, certifications, tariff classification restrictions, conditions by origin, etc.) when it detects the environmental risk.
The technical focus: “change of land use in forest land”
The “change of land use in forest lands” is a concept regulated within the forestry/environmental framework (and typically requires authorization). The reform in the Foreign Trade Law ties foreign trade to this front: if your production chain touches areas with potential forest character, the evidentiary standard rises.Cámara de Diputados)
Recurring risk in supply chain audits: “Mixed” (agricultural-forestry) properties, historical expansions of the agricultural frontier, informal leases or leases without a robust record, and incomplete traceability by collectors.
STPS labor certification for agricultural exports: what it is and what it is NOT
What do we know? (LFT 283 Quater)
The art. 283 Quater LFT empowers the STPS to issue a certificate of compliance with obligations labor and social security, subject to general provisions. (Cámara de Diputados)
What is still a gray area? (until the rules are released)
The standard does not yet define:
- yes it will be mandatory or “voluntary with commercial effects”;
- What universe does it cover: only the field?, all exporting companies?, by product, by company name, by workplace?;
- validity, grounds for suspension or revocation;
- interoperability with IMSS/SAT/INFONAVIT and digital records;
- whether it will function as a "pass" for customers/customs or as a requirement for certain procedures.
Strategic reading: Although presented as a certification, it will operate as commercial risk management toolGlobal customers, retailers, and industrial buyers can make it a contractual (or eligibility) condition, even before an authority formally requires it.
Practical impact on agricultural exporters and supply chains (agro/forestry)
If you export (or supply those who export), the impact is concentrated in three layers:
- OperationYou need files ready "on demand".
- payroll, contracts, work schedules, payroll/temporary lists, evidence of training, and safety and hygiene documents.
- Evidence of social security: affiliation and payments, subcontracting in accordance with applicable rules, and documentary consistency.
- ChainYour risk doesn't end on your property.
Purchases from producers, packers, collectors, or third parties. The LCE reform pushes the “environmental risk” to become traceable by lot, supplier, property, and geography. (Cámara de Diputados)
- Commercial/contracts: declarations and remedies are being toughened
You will see more clauses from:
- audit and access to information,
- termination for labor/environmental non-compliance,
- indemnities for penalties and withholdings,
- obligations to maintain certifications.
Does your agricultural export operation need to implement this reform in policies, contracts, and audit records? Baráibar & Asociados (CDMX) We can help you design a robust and defensible compliance plan. Schedule a consultation.
Risk matrix 2026: where companies fail most often
The following are typical “points of failure” that make the STPS certificate and the environmental cause critical in LCE:
1) Labor: temporary agricultural workers, underreporting and fragmented documentation
In the field, the risk is not only non-compliance, but also inability to prove it consistently across work centers, seasons, and contractors. The STPS certificate, if it becomes standard, will penalize informal documentation.Cámara de Diputados)
2) Social security: IMSS gaps due to mobility and third parties
Schemes with high turnover and labor providers are highly auditable. A “certificate” that combines labor and social security forces alignment:
- highs/lows,
- SBC,
- opportune whole,
- consistency between CFDI payroll and social security payments.
3) Environmental: properties, polygons and evidence of authorization
The LCE cause does not pursue “opinions”; it pursues demonstrable factsDeforestation/land use change without authorization. The real bottleneck will be the paperwork (titles, permits, plans, coordinates, supply contracts, batch traceability). (Cámara de Diputados)
4) Foreign trade: non-tariff requirements and sensitive tariff lines
The LCE stipulates that non-tariff measures will be implemented via prior permits, quotas, origin marking, certifications and other instruments. With the reform, “certification” ceases to be just a matter of quality: it also becomes a labor/environmental issue. (Cámara de Diputados)
How to prepare: a defensible compliance plan in 30–90 days
This is where a "premium" approach makes a difference: it's not about putting together papers, it's about building evidentiary capacity.
Step 1: Internal due diligence, “buyer audit” type
- map of work centers, seasons and labor providers;
- review of contracts, regulations, working hours, payments and receipts;
- consistency payroll-accounting-taxes-social security (without contradictions).
Step 2: STPS file ready for certification
Although we don't yet know the official checklist, a robust file typically includes:
- organizational chart and responsible parties,
- compliance policies,
- evidence of training and safety and hygiene,
- logs and minutes,
- contracts and payment receipts,
- traceability of seasonal temporary staff.
Step 3: Environmental traceability by supplier/property/batch
Your traceability system must be able to answer: From which property did this product originate, and what evidence supports the claim that there was no unauthorized change in the use of forest land?
Consolidate:
- supplier onboarding,
- contractual statements,
- documentary verification,
- sample audits,
- mechanisms for terminating and replacing suppliers.
Step 4: Contracts: turning compliance into an operational obligation
Update supply/manufacturing/purchase agreements with:
- obligation to provide periodic evidence,
- audits and right of visit,
- obligation to notify investigations/sanctions,
- proportionate and enforceable remedies (withholding, substitution, rescission).
Don't face this process alone. Baráibar & Asociados We have specialists in foreign trade and labor compliance ready to defend your interests in Mexico City.
What's next: realistic scenarios following the publication of STPS rules
There are three plausible scenarios (and they are not mutually exclusive):
- Certification as a commercial “fast-track”
Buyers demand it as a supplier standard; those who do not have it are excluded from bids/contracts.
- Certification as a requirement in procedures or programs
It can be indirectly linked to authorizations or facilitation schemes; even without calling it "mandatory", the market makes it indispensable.
- Certification as a basis for focused inspection
The existence of a formal instrument creates a "map" of certified/non-certified companies. This can influence inspections, audits, and reviews.
In parallel, the environmental grounds in LCE enable sectoral measures (by product or fraction) where the risk of deforestation/land use change is high. (Cámara de Diputados)
Conclusion
The reform of May 1, 2026 It's not just "more regulation": it's a change in architecture. Foreign trade can now rely more explicitly on ecology (including deforestation/land use change) and in work/social security to justify measures. And the STPS obtains an instrument (certification) that, by design, can become market access currency. (Cámara de Diputados)
CTA 3 (before the final conclusion)
Secure your business position and reduce risks with expert legal support from Baráibar & Asociados in Mexico City: compliance, contracts and evidentiary strategy.
FAQs (real searches in Mexico)
1) What is the labor compliance certificate for agricultural exports?
It is a certificate that the STPS may issue to certify compliance with obligations labor and social security, provided for in the Article 283 Quater of the LFT. Su trámite dependerá de disposiciones generales que emitan autoridades competentes. (Cámara de Diputados)
2) Is the STPS certificate now mandatory for exporting?
The Decree only empowers the STPS to issue it and orders the issuance of rules within 30 days; it does not, in itself, establish a universal obligation to export. However, it may become enforceable through subsequent rules or contracts with buyers.Cámara de Diputados)
3) What changed in the Foreign Trade Law regarding environmental issues?
The art. 15, section IV to include prevention of deforestation and change of land use in forest lands without authorization, and the fracción VI to include ecology (and connection with work/social security) as a basis for measures. (Cámara de Diputados)
4) What type of measures can foreign trade impose for these reasons?
The LCE provides for non-tariff measures such as prior permits, quotas, origin marking, certifications and other instruments, identifiable by tariff classification. The reformed grounds allow for their design when there is an environmental/labor risk according to the assumption. (Cámara de Diputados)
5) How does this reform affect companies that buy from independent producers?
Raises the standard of due diligenceThe leading company may need to demonstrate traceability and compliance in its supply chain to sustain exports or contracts. The reform aims to prevent environmental risks (deforestation/land use change) that often materialize upstream. (Cámara de Diputados)
6) What documents should be prepared for an STPS labor certification?
Although regulations are lacking, it is advisable to structure the evidentiary file: contracts, receipts and timesheets; evidence of safety and hygiene; records of temporary personnel; and consistency of social security compliance. Rationale: art. 283 Quater LFT and transitional procedural rules. (Cámara de Diputados)
Official references (with latest update and URL)
- Decreto DOF 01/05/2026 (Edición Vespertina) – “Se reforman… Ley de Comercio Exterior… y se adiciona el art. 283 Quáter LFT…” – Publicado 01-may-2026.
https://www.diputados.gob.mx/LeyesBiblio/ref/lce/LCE_ref06_01may26.pdf (Cámara de Diputados)
- Ley de Comercio Exterior (texto vigente Cámara de Diputados) – (incluye nota “Fracción reformada DOF 01-05-2026” en art. 15).
https://www.diputados.gob.mx/LeyesBiblio/pdf_mov/Ley_de_Comercio_Exterior.pdf (Cámara de Diputados)
- Ley Federal del Trabajo (texto vigente Cámara de Diputados) – “Últimas Reformas DOF 01-05-2026” e incorporación del art. 283 Quáter.
https://www.diputados.gob.mx/LeyesBiblio/pdf/LFT.pdf (Cámara de Diputados)
- Ley General de Desarrollo Forestal Sustentable (Cámara de Diputados) – marco sobre ecosistemas forestales y conceptos vinculados a cambio de uso de suelo.
https://www.diputados.gob.mx/LeyesBiblio/pdf/LGDFS.pdf (Cámara de Diputados)
- Ley General del Equilibrio Ecológico y la Protección al Ambiente (Cámara de Diputados) – bases de preservación y protección ambiental.
https://www.diputados.gob.mx/LeyesBiblio/pdf/LGEEPA.pdf (Cámara de Diputados)
Disclaimer: “This article is for informational purposes only and does not constitute legal advice or an attorney-client relationship.”
by paulina@baraibar.com.mx | May 12, 2026 | Criminal law
Criminal act It can no longer be treated as an “automatic” phrase to justify a arrest warrant or a order to proceed to trialSince March 2026, a mandatory criterion emphasizes that, by last ratio and the guarantor function of the criminal type, the Prosecutor's Office must provide minimum test data that show in fact the basic characteristics of the alleged crime, before affecting freedom (article 16 of the Constitution).
In practice, this standard reorders the debate: it is not enough to narrate, one has to minimally checkFor companies and individuals under investigation in Mexico City, this opens a clear defensive avenue to combat "generic" accusations and, at the same time, compels them to strengthen compliance strategies and evidence management.
1) What changed in 2026: “criminal act” as the minimum verifiable factual element
The widely disseminated criterion as “CRIMINAL ACT. ITS BASIC CONNOTATION IN LIGHT OF THE PRINCIPLES OF LAST RESORT AND GUARANTEE FUNCTION OF THE CRIMINAL TYPE” It upholds an operational idea: the “criminal act” of Article 16 of the Constitution requires a minimum evidentiary sufficiency that shows, in the factual world, a behavior with basic features of the criminal offense preliminarily attributed. That burden falls on the Prosecutor's Office and is essential requirement both for arrest warrant as for link to process, due to its direct or indirect impact on freedom.
Why does it matter for an arrest warrant (art. 16 CPEUM)
Article 16 of the Constitution requires (among other things) that get data that establish that the act has been committed and that there is a probability of participation.
The point of criterion 2026 is that this “fact” cannot be an empty label: it must have minimum anchorage in test data that show the basic materiality of typical behavior.
Why does it matter for indictment (art. 316 CNPP)
Article 316 of the CNPP requires evidence establishing that an act defined as a crime by law was committed, understanding that such evidence exists when there is reasonable indications that allow one to suppose.
The 2026 criterion pushes for those “reasonable indications” to translate into verifiable factual features of the criminal type, not only in broad inferences.
2) Date of mandatory nature and actual procedural scope
This criterion was published in the Weekly March 6, 2026 and it was considered mandatory application from 9 March 2026.
Practical scope:
- It becomes a control parameter for control judges when analyzing arrest requests and to resolve link to process.
- The cost of litigating with "textbook" charges increases: if the prosecution does not ground the criminal offense in verifiable facts, the defense has a technical argument to deny, revoke o protect.
⚖️ spin: Do you have questions about this topic? The lawyers at Baráibar & Asociados in Mexico City can guide you. Schedule your consultation today.
3) The core of the criterion: last resort + guarantee function of the criminal type
The criterion explains that criminal law, being last ratioIt must be used with a reinforced standard when the procedural act affects liberty. Furthermore, the guarantee function of the criminal type requires that only the commission of conduct typified (and not “similar”) justify intense measures such as apprehension or continuation of the process.
What does “guarantee function” mean in litigation language?
In court proceedings, the "guarantee function" translates into control:
- Delimit the punishable conduct (what is and is not included in the type).
- Demand that the Prosecutor's Office show basic facts that coincide with that framework.
- To prevent the process from being used as an "extended investigation" with already restricted freedom.
Last resort as a minimum evidentiary standard, not as discourse
The criterion does not say "prove the complete crime" at the initial stage. It says: contribute the minimum verifiable amount of the type charged, because the State is using its most powerful tool. That difference is key: it's not a request for an early sentence, it's a demand. factual floor.
4) Arrest warrant: where the Prosecutor's request breaks with this standard
In the CNPP, the judge can order a summons, appearance, or apprehension When a complaint is filed, the Public Prosecutor's Office announces data that establishes the criminal act and the probability of authorship, and—for apprehension— need for caution.
Using the 2026 criterion, typical vulnerable points are:
A) “Generic” facts without typical features
Example: “seized resources”, “defrauded”, “threatened”, “altered documents”, without describing as, when, with what medium, with what resultand without supporting data. The standard requires showing basic characteristics of the type (conduct/object/result relevant to the crime).
B) Inferential leaps without hard data
When the Prosecutor requests arrest with inferences (“because of his position he should have known”, “he had access”, “he is an administrator”), without minimal external data (traceability, messages, preliminary expert reports, records, witnesses with verifiable context).
C) “Need for caution” as a crutch
Although the criterion focuses on "criminal act", in practice it requires reviewing whether the apprehension is being used to drive without basic factual support. If the "fact" is weak, the caution becomes disproportionate.
Typical business risk (CDMX): Internal complaints or those from former employees that escalate to a formal case file; if the company fails to preserve evidence and a clear narrative, the prosecution can fill in the gaps with assumptions. This criterion makes it more cost-effective to litigate the standard from the outset.
5) Linking to the process: the debate is no longer just a probability of participation
Article 316 CNPP requires evidence of the criminal act and the probability of intervention.
The 2026 criterion strengthens the first component: criminal act as verifiable minimum factual of the basic characteristics of the crime.
How to use it strategically in initial audiences:
- Separate The discussion: first “criminal act” (factual basis), then “probability”.
- Ask the judge to identify what basic typical features They are considered satisfied and with what information (not with what “said”).
- Attacking the “minimum typicality” when the imputation is narrative but not verifiable.
Common defensive mistakes (that you should avoid):
- Discussing “innocence” or “full proof” (is not the standard).
- To go straight to subtle contradictions without first addressing the lack of basic features of the type.
- Do not tie the argument to the impact on freedom (precautionary measures, appearances, reputational restriction, etc.).
Don't face this process alone. At Baráibar & Asociados, we have criminal law specialists ready to defend your interests in Mexico City.
6) Tactical checklist: what the prosecution should provide and what the defense should demand
This criterion functions as a litigable checklist.
The minimum that must exist (depending on the crime)
Without inventing “universal lists”, the logic is: basic features of the type + minimum test data that makes them verifiable.
Examples of “minimum verifiable” (in the abstract):
- Assets: traceability of disposal, specific impact, base document/record, identification of the asset/value.
- Documentaries: existence of the document, attributed intervention, preliminary expertise or verifiable objective feature.
- Threats/violence: context, medium, basic content, temporality, objective element that supports the claim.
How to structure a defensive objection
- “Your Honor, even if the narrative is granted for now, no minimum data that factually demonstrate the basic characteristics of criminal type X; due to its guarantee function and as a last resort, freedom cannot be affected by an unverifiable fact.”
Risk: that the judge “supplants” the standard
The real danger is that the judge will mentally "fill in the gaps" left by the prosecution ("it sounds like fraud"). This criterion provides grounds for demanding a more thorough ruling. methodical: typical feature + fact.
7) Impact on companies: criminal compliance and evidence management from day 1
For companies (fintech, retail, construction, logistics, pharma, tech) the 2026 standard has two interpretations:
1) More powerful early defense
If the case file was built with vague testimonies or disconnected documents, the defense can halt the arrest/indictment with an approach of verifiable minimum typicality.
2) Greater internal demands
Companies must quickly build their "verifiable factual explanation":
- Preservation of emails/chats, logs, accounting records.
- Internal chain of custody (without replacing the authority, but avoiding destruction/alteration).
- Internal research protocols (to avoid creating contradictions that could later be used as "facts" against the company or its executives).
Frequent gray area: Poorly documented internal investigations that create “facts” without technical support. The 2026 criterion rewards accuracy and penalizes narrative.
8) Protection strategy: when this criterion is decisive
Judgment itself is built in scenarios of arrest warrant and link to process, and states that Article 16 requires that minimum threshold.
When is it usually decisive:
- When the judicial resolution does not identify what data support the basic characteristics of the crime.
- When the Public Prosecutor "announces" data, but in court it does not translate into verifiable facts.
- When the resolution relies on standard phrases (“reasonable indications”) without explanation indicios de qué.
How this translates into procedural risk for the Prosecutor's Office:
- Higher probability of revocation/denial,
- Greater exposure to protection due to insufficient motivation,
- Greater pressure to "strengthen" cases before requesting restrictive measures.
Protect your freedom and your defense strategy with expert legal advice from Baráibar & Asociados in Mexico City.
Conclusion
The mandatory criterion of March 2026 redefines the concept of criminal act in its correct place: a verifiable minimum factual that the Prosecutor's Office must show to justify measures that impact freedom, consistent with the last ratio and the guarantor function of the criminal type.
For criminal defense (and for business risk management) the message is clear: litigation is no longer won with rhetoric; it is won by forcing the criminal type to land on verifiable basic facts, from the first act that intends to restrict rights.
FAQs (Mexico) — Snippet-type answers (45–60 words)
1) What is a “criminal act” for the purposes of an arrest warrant?
The reported fact is that la ley señala como delito, supported by data that allow establishing what occurred and that there is a probability of participation. The constitutional standard derives from Article 16 of the Mexican Constitution and is operationalized in the National Code of Criminal Procedure. In 2026, it was emphasized that there must be a verifiable minimum of facts.
2) Does the prosecution have to prove the entire crime in order to bring charges?
No. For linkage, the CNPP requires test data e reasonable indications, not conclusive proof. However, there must be a verifiable minimum of the basic features of the imputed crime, in accordance with the mandatory criterion of 2026 and article 316 CNPP.
3) What happens if the arrest warrant is based on generic facts?
If the application and the resolution do not show minimum data that factually demonstrate the basic characteristics of the crime, a violation of article 16 CPEUM can be argued due to the insufficiency of the "criminal act", and judicial control or protection can be sought as appropriate.
4) Since when is the criterion “CRIMINAL ACT. ITS BASIC CONNOTATION…” mandatory?
It was published on March 6, 2026 and it was considered mandatory from March 9, 2026, according to the Gazette of the Judicial Weekly of the Federation. This impacts decisions regarding arrest and indictment.
5) How does Article 141 of the CNPP relate to the “criminal act”?
Article 141 of the CNPP allows for summons, appearance, or arrest when there is a complaint/accusation and the Public Prosecutor presents information establishing the criminal act and the probability of authorship; for arrest, there is also a need for precautionary measures. Criterion 2026 requires that this “act” have a minimum verifiable factual basis.
6) What should the defense request in the hearing to apply this standard?
It must require the judge to identify what basic features of the criminal type are considered satisfied and with what information specific, avoiding generic motivations. The basis is in article 16 CPEUM, 316 CNPP and the mandatory criterion of 2026 on “criminal act”.
References (official) + latest reform
Disclaimer: This article is for informational purposes only and does not constitute legal advice or an attorney-client relationship.
SEO Summary
- Focus Keyphrase:
- Keywords secundarias: artículo 16 constitucional, artículo 316 CNPP, artículo 141 CNPP, última ratio penal, función garantista del tipo penal, datos de prueba mínimos, juez de control CDMX, defensa penal estratégica
- Meta Description: Criminal act in 2026: minimum verifiable standard for arrest warrant and indictment. Avoids risks and nullities.
- Meta Title: Criminal act and arrest/indictment order: minimum verifiable standard 2026
- Slug SEO: hecho-delictivo-orden-aprehension-vinculacion-estandar-minimo-2026
- Breadcrumb: Inicio > Penal > Hecho delictivo y órdenes de aprehensión 2026
- Categoría: Penal
- Intención de búsqueda: preventiva + informacional (con componente transaccional)
- Outbound links: CPEUM Diputados; CNPP Diputados; Gaceta SCJN (PDF)
- Internal links (sugeridos): “Amparo contra orden de aprehensión en CDMX”; “Audiencia inicial y vinculación a proceso: estrategia”; “Medidas cautelares: riesgos y defensa”
- Keyphrase Density (estimada): 0.8%–1.2%
- Flesch estimado: 58–63
- Voz pasiva estimada: < 12%
- “Orden de aprehensión en CDMX: cómo combatir la necesidad de cautela (2026)”
- Keyword: necesidad de cautela orden de aprehensión
- Intención: preventiva/defensiva
- Relación: complementa el estándar de hecho delictivo con el eje cautelar
- Potencial comercial: defensa en audiencia y amparo
- “Vinculación a proceso: cómo desmontar imputaciones genéricas con el artículo 316 CNPP (2026)”
- Keyword: artículo 316 CNPP vinculación a proceso
- Intención: informacional + transaccional
- Relación: baja a técnica de audiencia inicial
- Potencial comercial: litigio estratégico penal
- “Evidencia digital y datos de prueba mínimos: guía de preservación para empresas investigadas (CDMX 2026)”
- Keyword: preservación de evidencia digital empresa investigación penal
- Intención: preventiva/compliance
- Relación: fortalece el “mínimo verificable” desde el día 1
- Potencial comercial: compliance penal corporativo y gestión de crisis